On the payroll?
Full-time, part-time and casual employees. I’ll look at your income, employment history and the bigger picture.
 ↗ 0450 236 240
The car. The work ute. The big business plan. Tell me where you want to go, and I’ll compare suitable finance options to help you get there.
An initial chat won’t affect your credit score.
Formal applications may involve a credit enquiry.
From the daily drive to the tools of your trade.
Let’s work out what’s possible.
New and used cars, utes and SUVs. Buy through a dealer or private seller, with pre-approval options before you shop.
YOUR NEXT SET OF KEYSISSUE 02Trucks, vans and work utes. Explore vehicle finance for your business, whether you’re on the tools or on the road.
PUT YOUR PLANS TO WORKISSUE 03Motorbikes, boats, caravans and jet skis. Let’s explore the options for your next adventure.
HELLO, WEEKEND PLANSISSUE 04Forklifts, machinery and business equipment. Finance the gear that helps you get the job done.
GEAR UP FOR GROWTHISSUE 05Explore funding for working capital and business cash-flow needs, based on your business and its circumstances.
KEEP BUSINESS MOVINGISSUE 06Have a personal expense or another goal in mind? Tell me the purpose and we’ll explore suitable personal loan options.
A PLAN THAT FITS YOUR LIFEAll finance is subject to lender criteria, assessment and approval. Available products, terms and documentation vary.
Different jobs. Different incomes. Different credit histories. Let’s start with your situation and see what may be possible.
Full-time, part-time and casual employees. I’ll look at your income, employment history and the bigger picture.
Self-employed applicants and ABN holders. Full-doc, low-doc and self-declared income options may be available, depending on the lender and product.
New and established businesses seeking vehicles, equipment or cash-flow funding. Trading history and documentation requirements vary.
First-time borrowers who want a clear explanation of the process, the paperwork and the available options.
Good credit, low scores or past credit issues—including defaults. I’ll understand your circumstances before exploring suitable options.
Applicants receiving Disability Support Pension income may be considered by selected lenders, subject to income acceptance, affordability and other criteria.
Temporary residents and eligible visa holders. Options depend on your visa type, remaining visa term and the lender’s requirements.
Buyers purchasing through a dealership or privately. I’ll guide you through the checks and documents for your purchase.
These are situations I can assess—not promises of approval. Suitability, affordability and lender criteria always apply.
What are you buying? What’s your budget? We start with a conversation about you.
I assess your circumstances and compare suitable options through my lender panel.
I explain the option, help with the paperwork and guide you through to settlement.
I’m Samir, the face behind That Peaky Broker. I’ve worked across dealerships and broker firms, and I’ve personally experienced defaults. I know what it feels like to be overlooked.
That’s why I take the time to understand your situation first. Clear explanations, suitable lender options and a real person in your corner.
I compare suitable finance options from a broad lender panel. The aim is to find a fit for your circumstances, before submitting an application.
Find out what could suit you ↗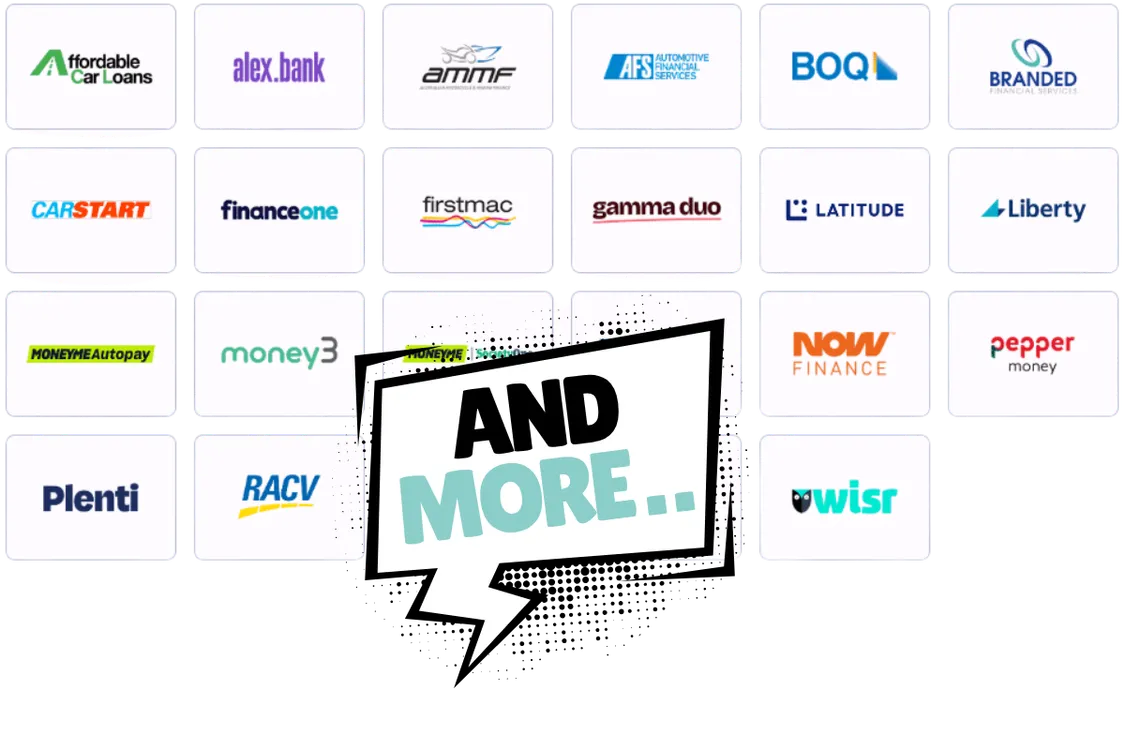
Finance doesn’t need its own translator.
No. An initial conversation doesn’t automatically put an enquiry on your credit file. I’ll understand your situation first and explain when a formal application may involve a credit check.
Yes, depending on the lender and transaction. Private-sale finance may require additional checks and documents. I’ll explain what’s required before you buy.
Not always. It depends on the vehicle, purchase price, lender and your circumstances. A deposit can reduce the amount borrowed, but every scenario is different.
No. Every application is subject to lender criteria and assessment. I can assess your circumstances and compare suitable options before an application is submitted.
Potentially, yes. Documentation requirements vary. Some lenders require financials and tax returns; certain products may allow alternative income verification.
Credit issues don’t automatically rule out finance. I’ll need to understand what happened, when it occurred and what your financial position looks like now. Lender criteria and affordability still apply.
The initial enquiry takes around 5–10 minutes. From there, timing depends on the lender, your circumstances and whether all required documents are available.
Common requirements include identification, income evidence, employment details and information about the asset. Bank statements or business documents may also be requested. I’ll give you a list for your situation.